
Rekenbox · 2026
Corporate tax calculator Netherlands
Corporate tax by bracket, loss relief and net dividends. Compare money retained, moved to a holding and distributed personally.Example calculation — adjust the amounts to your situation.Without a dividend distribution. To see net dividends, open “Also calculate dividends”.
From profit to funds
What remains?
- Corporate tax
- €50,900.00
- Box 2
- €0.00
- After tax
- €199,100.00
Corporate tax brackets
Quarterly reserve
€12,725.00When distributed personally · 2026
- Gross dividend
- €0.00
- Total box 2
- €0.00
- Already withheld (15%)
- €0.00
- Net dividend
- €0.00
The 15% is a prepayment within the box 2 charge. It is not added on top of the box 2 rate.
- Profit after any director pay deduction
- €250,000.00
- Participation exemption, net
- €0.00
- Qualifying innovation-box profit
- €0.00
- Innovation base reduction (1 − 9/25.8)
- €0.00
- Taxable profit before loss relief
- €250,000.00
- Losses used
- €0.00
- Losses available for later years
- €0.00
- Taxable amount
- €250,000.00
- Corporate tax first €200,000 · 19%
- €38,000.00
- Corporate tax above €200,000 · 25.8%
- €12,900.00
- Effective corporate tax (%)
- 20.36
- Gross dividend
- €0.00
- Box 2 on this distribution
- €0.00
- Dividend withholding credited against final tax
- €0.00
- Remaining box 2 after withholding
- €0.00
- Profit retained in the operating company
- €199,100.00
- Corporate and box 2 tax / profit (%)
- 20.36
- Quarterly corporate-tax reserve
- €12,725.00
- Suggested provisional assessment for this financial year
- €50,900.00
Findings and points to check
- Formal loss decisions, changes in ownership and special loss restrictions are not assessed. The quarterly reserve divides the annual estimate; it is not a Tax Administration payment schedule.
Allocation if distributed directly to individuals
| Shareholder | Ownership % | Gross dividend € | Box 2 low € | Box 2 high € | Withheld € | Net personal € |
|---|---|---|---|---|---|---|
| Aandeelhouder 1 | 100 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
Operating company, holding or individuals
| Destination | Amount after tax € | Meaning |
|---|---|---|
| Retain in operating company | 199100.00 | Later distribution may incur box 2 |
| To qualifying holding | 0.00 | Only with participation and withholding exemptions; not personal funds yet |
| To individuals | 0.00 | After box 2; 15% withholding is included in it |
Assumptions, sources and version
2026 · nl-corporate-2026.1 · v2026.1
- Dutch company under ordinary corporate tax with Dutch-resident substantial-interest shareholders. No fiscal unity, foreign tax, box 2 losses or personal deductions.
- 15% dividend withholding is credited against box 2 tax. This model does not assess distribution tests, reserves or formal loss and exemption decisions.
- Corporate and box 2 tax are estimated to cents; returns and assessments use whole-euro rounding. Director pay assumes a person below state pension age without employee insurance and with personal healthcare contributions.
- Belastingdienst — tarieven vennootschapsbelasting (2026-09-07)
- Belastingdienst — box 2 (2026-09-07)
- Belastingdienst — gebruikelijk loon (2026-09-07)
- Belastingdienst — verliesverrekening (2026-09-07)
- Belastingdienst — drempel innovatiebox (2026-09-07)
- Wet Vpb — artikel 12b, innovatieboxgrondslag 9/H (2026-09-07)
- Belastingdienst — deelnemingen (2026-09-07)
- Belastingdienst — dividendbelasting als voorheffing (2026-09-07)
- Belastingdienst — belastbaar bedrag en boekjaar (2026-09-07)
- Belastingdienst — inkomstenbelasting 2024–2026 (2026-09-07)
- Belastingdienst — arbeidskorting 2024 (2026-09-07)
- Belastingdienst — arbeidskorting 2025 (2026-09-07)
- Belastingdienst — algemene heffingskorting 2025 (2026-09-07)
Rather outsource it?
Want your tax return handled?
A dedicated Winstwaker bookkeeper prepares your income tax or corporate tax return. Work and price are agreed in writing first.
See tax returns by Winstwaker ↗Report for your records
Turn this into a complete PDF report.
Combine inputs, results, calculation rules and sources in a dossier for your accountant, lender or business customer.
- Result with the full calculation
- Assumptions and sources, so others can verify it
- Your inputs and calculation version recorded
The same calculation as above, fully documented. View the free preview first; you only pay when you want to download the report. See pricing
For the preview, we store your inputs encrypted on our server: 30 days without an account, or until you delete it once linked to your email.
Bulk · Calculate your entire list
Save on this device for free
Understand your result
How this tool works
Corporate income tax is charged on a Dutch company’s taxable amount. That amount is not always the same as accounting profit. Exempt participation results, substantiated innovation-box adjustments and available losses can change the base. This calculator displays those steps separately. Calculate for 2024, 2025 or 2026 and independently choose the calendar year in which a dividend is paid.
Ordinary corporate rates are identical across these three years: 19% on the first €200,000 and 25.8% above that amount. The calculator separates the brackets and shows effective tax pressure. That percentage can be below the highest rate because only the upper portion enters the second bracket. Negative taxable profit produces no corporate tax for that year but may create a usable loss.
Loss relief is limited to the first €1 million of profit plus 50% of the excess. Enter only losses actually available. A separate multi-year series follows consecutive years, applies a new loss to the preceding year where possible, then carries the remainder forward. Special restrictions, such as those arising from ownership changes, are not assessed. Retain formal loss decisions and relevant advice.
The participation table removes only entries whose exemption you confirm. A negative exempt participation result is adjusted too. Innovation-box profit requires substantiated allocation, a threshold and a nexus percentage. The model includes 9/25.8 of qualifying benefits in the taxable base, after which ordinary brackets apply. It is not a separate 9% charge that can be applied unconditionally to all company profit.
After corporate tax, enter gross dividends and allocate them among substantial-interest shareholders. Box 2 brackets are applied per shareholder, considering entered other box 2 income. The 15% dividend withholding is an advance payment within the final charge. With a qualifying holding company, funds remain business assets; the calculation also displays the direct personal distribution alternative.
The optional director-pay comparison includes annual income tax, credits and a personal healthcare contribution for the first shareholder below state pension age. Indicate whether salary has already been deducted from profit. A quarterly reserve divides the annual estimate into four portions. No distribution test, return or provisional assessment is submitted automatically; review the complete circumstances before acting on the figures.
Corporate brackets in 2024, 2025 and 2026
19% × min(taxable amount, €200,000) + 25.8% × excess
Corporate rates are unchanged, while box 2 thresholds and director-pay parameters vary by calendar year.
Apply losses within the limit
Loss capacity = min(profit, €1 million) + 50% × profit above €1 million
At €9 million profit and €7 million losses, €5 million can be used. €4 million remains taxable and €2 million losses carry forward.
Read dividend withholding and box 2 together
Net dividend = gross dividend − final box 2 charge
The 15% withholding is credited. A holding distribution is withholding-free only when the relevant exemptions apply.
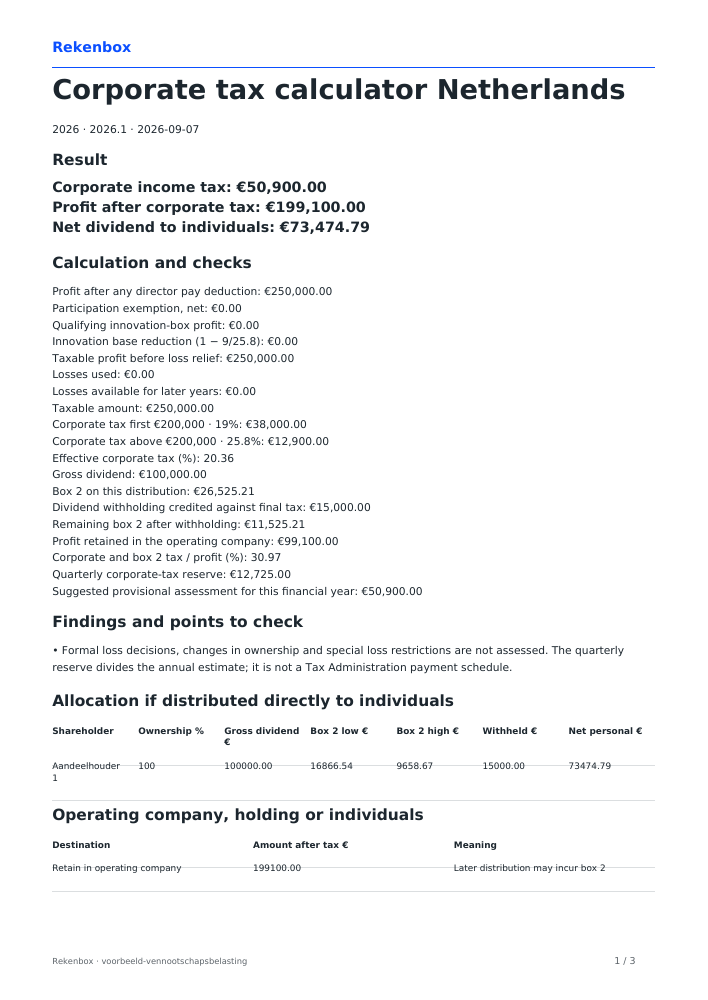
This PDF sample uses the visible example inputs. Your own download uses your entered information.
View sample · PDFCommon questions
How much corporate tax does a Dutch company pay in 2026?
19% on the first €200,000 taxable amount and 25.8% above it. Exemptions and losses first determine that amount.
How long can corporate losses be relieved?
In the ordinary model, one year back and indefinitely forward, subject to the annual profit limit and any special restrictions.
Do I pay 15% withholding on top of box 2?
No. It is credited against final box 2 tax. The calculator shows the remaining amount.
Can I calculate a non-calendar financial year?
Yes, within 2024–2026. The corporate bracket stays €200,000 per financial year. Dividends and director pay use a separate calendar year.
Are funds in my holding already net personal wealth?
No. Funds remain business assets. A later personal distribution can still incur box 2.
Which details do you need?
- Profit before exemptions and loss relief below
- Tax year / distribution year
- Available losses carried forward
- Desired gross dividend
- Number of substantial-interest shareholders
- Calendar year of dividend and director pay
- Customize shares and other box 2 income
- Shareholder allocation
- Dividend destination
- The holding qualifies for participation and withholding exemptions
- Income already included in profit
- Profit allocated to innovation (%)
- Unrecovered innovation-box threshold
- Established nexus percentage (%)
- Qualification and profit allocation are substantiated
- Non-calendar or irregular financial year
- Financial year start
- Financial year end
- Include director pay in combined tax
- Gross director salary for the calendar year
- This director salary is already deducted from entered profit
- Track losses across several years
- Annual profits after tax adjustments, before loss relief
Limits of this tool
- Dutch company under ordinary corporate tax with Dutch-resident substantial-interest shareholders. No fiscal unity, foreign tax, box 2 losses or personal deductions.
- 15% dividend withholding is credited against box 2 tax. This model does not assess distribution tests, reserves or formal loss and exemption decisions.
- Corporate and box 2 tax are estimated to cents; returns and assessments use whole-euro rounding. Director pay assumes a person below state pension age without employee insurance and with personal healthcare contributions.
Year: 2026, 2025, 2024 · Version 2026.1
Sources for this tool
- Belastingdienst — tarieven vennootschapsbelasting · calculation source checked 2026-09-07
- Belastingdienst — box 2 · calculation source checked 2026-09-07
- Belastingdienst — gebruikelijk loon · calculation source checked 2026-09-07
- Belastingdienst — verliesverrekening · calculation source checked 2026-09-07
- Belastingdienst — drempel innovatiebox · calculation source checked 2026-09-07
- Wet Vpb — artikel 12b, innovatieboxgrondslag 9/H · calculation source checked 2026-09-07
- Belastingdienst — deelnemingen · calculation source checked 2026-09-07
- Belastingdienst — dividendbelasting als voorheffing · calculation source checked 2026-09-07
- Belastingdienst — belastbaar bedrag en boekjaar · calculation source checked 2026-09-07
- Belastingdienst — inkomstenbelasting 2024–2026 · calculation source checked 2026-09-07
- Belastingdienst — arbeidskorting 2024 · calculation source checked 2026-09-07
- Belastingdienst — arbeidskorting 2025 · calculation source checked 2026-09-07
- Belastingdienst — algemene heffingskorting 2025 · calculation source checked 2026-09-07
Prepared by the Rekenbox product team at Winstwaker. The listed source references and calculation version make the method traceable. Report a content error Last updated: 2026-09-07. Rekenbox is a product by Winstwaker. The tool applies a calculation model to your inputs; a result or paid report is not a personal assessment by an adviser.