
Rekenbox · 2026
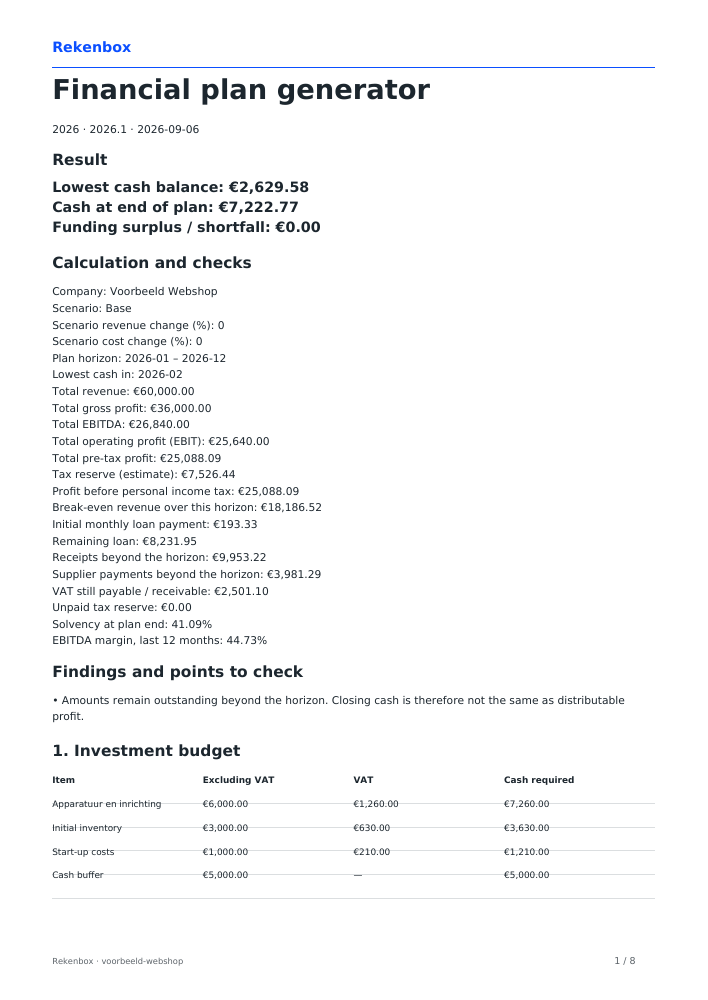
Investment budget
Create four connected budgets. See profit, funding and cash for 12 to 36 months.Looking ahead
Room to run your business.
Cash at each month end. Select a bar for amounts; red means additional funds are needed.
- Closing cash
- €2,858.34
- Receipts
- €136.62
- Profit
- €270.00
- Principal
- €143.33
View ratios for your closing balance and last twelve forecast months. Other loans are treated conservatively as current debt; review their maturity. Supply historical comparatives yourself.
- Company
- Voorbeeld Webshop
- Scenario
- Base
- Scenario revenue change (%)
- 0
- Scenario cost change (%)
- 0
- Plan horizon
- 2026-01 – 2026-12
- Lowest cash in
- 2026-02
- Total revenue
- €60,000.00
- Total gross profit
- €36,000.00
- Total EBITDA
- €26,840.00
- Total operating profit (EBIT)
- €25,640.00
- Total pre-tax profit
- €25,088.09
- Tax reserve (estimate)
- €7,526.44
- Profit before personal income tax
- €25,088.09
- Break-even revenue over this horizon
- €18,186.52
- Initial monthly loan payment
- €193.33
- Remaining loan
- €8,231.95
- Receipts beyond the horizon
- €9,953.22
- Supplier payments beyond the horizon
- €3,981.29
- VAT still payable / receivable
- €2,501.10
- Unpaid tax reserve
- €0.00
- Solvency at plan end
- 41.09%
- EBITDA margin, last 12 months
- 44.73%
Findings and points to check
- Amounts remain outstanding beyond the horizon. Closing cash is therefore not the same as distributable profit.
1. Investment budget
| Item | Excluding VAT | VAT | Cash required |
|---|---|---|---|
| Apparatuur en inrichting | €6,000.00 | €1,260.00 | €7,260.00 |
| Initial inventory | €3,000.00 | €630.00 | €3,630.00 |
| Start-up costs | €1,000.00 | €210.00 | €1,210.00 |
| Cash buffer | €5,000.00 | — | €5,000.00 |
2. Financing budget
| Funding source | Amount |
|---|---|
| Owner capital | €7,100.00 |
| Loan | €10,000.00 |
| Other funding | €0.00 |
| Total available | €17,100.00 |
| Required including buffer | €17,100.00 |
| Surplus / shortfall | €0.00 |
3. Monthly operating budget
| Month | Revenue | Cost of goods | Gross profit | Fixed costs | Start-up costs | Depreciation | EBIT | Interest | Pre-tax profit | Tax reserve | Profit before personal income tax |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 2026-01 | €3,500.00 | €1,400.00 | €2,100.00 | €680.00 | €1,000.00 | €100.00 | €320.00 | €50.00 | €270.00 | €81.00 | €270.00 |
| 2026-02 | €3,500.00 | €1,400.00 | €2,100.00 | €680.00 | €0.00 | €100.00 | €1,320.00 | €49.28 | €1,270.72 | €381.22 | €1,270.72 |
| 2026-03 | €4,000.00 | €1,600.00 | €2,400.00 | €680.00 | €0.00 | €100.00 | €1,620.00 | €48.56 | €1,571.44 | €471.43 | €1,571.44 |
| 2026-04 | €4,000.00 | €1,600.00 | €2,400.00 | €680.00 | €0.00 | €100.00 | €1,620.00 | €47.84 | €1,572.16 | €471.65 | €1,572.16 |
| 2026-05 | €4,500.00 | €1,800.00 | €2,700.00 | €680.00 | €0.00 | €100.00 | €1,920.00 | €47.11 | €1,872.89 | €561.87 | €1,872.89 |
| 2026-06 | €4,500.00 | €1,800.00 | €2,700.00 | €680.00 | €0.00 | €100.00 | €1,920.00 | €46.38 | €1,873.62 | €562.09 | €1,873.62 |
| 2026-07 | €4,500.00 | €1,800.00 | €2,700.00 | €680.00 | €0.00 | €100.00 | €1,920.00 | €45.65 | €1,874.35 | €562.31 | €1,874.35 |
| 2026-08 | €4,500.00 | €1,800.00 | €2,700.00 | €680.00 | €0.00 | €100.00 | €1,920.00 | €44.91 | €1,875.09 | €562.53 | €1,875.09 |
| 2026-09 | €5,500.00 | €2,200.00 | €3,300.00 | €680.00 | €0.00 | €100.00 | €2,520.00 | €44.17 | €2,475.83 | €742.75 | €2,475.83 |
| 2026-10 | €6,000.00 | €2,400.00 | €3,600.00 | €680.00 | €0.00 | €100.00 | €2,820.00 | €43.42 | €2,776.58 | €832.97 | €2,776.58 |
| 2026-11 | €7,000.00 | €2,800.00 | €4,200.00 | €680.00 | €0.00 | €100.00 | €3,420.00 | €42.67 | €3,377.33 | €1,013.20 | €3,377.33 |
| 2026-12 | €8,500.00 | €3,400.00 | €5,100.00 | €680.00 | €0.00 | €100.00 | €4,320.00 | €41.92 | €4,278.08 | €1,283.42 | €4,278.08 |
Operating budget by forecast year
| Forecast year | Revenue | Cost of goods | Gross profit | Fixed costs | Start-up costs | Depreciation | EBIT | Interest | Pre-tax profit | Tax reserve | Profit before personal income tax |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | €60,000.00 | €24,000.00 | €36,000.00 | €8,160.00 | €1,000.00 | €1,200.00 | €25,640.00 | €551.91 | €25,088.09 | €7,526.44 | €25,088.09 |
4. Cash-flow forecast
| Month | Opening cash | Funding | Customer receipts | Suppliers | Operating payments | Initial spending | Interest | Principal | VAT paid / refunded | Income/corporate tax paid | Personal drawings | Closing cash |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2026-01 | €0.00 | €17,100.00 | €136.62 | €54.65 | €749.30 | €12,100.00 | €50.00 | €143.33 | €0.00 | €81.00 | €1,200.00 | €2,858.34 |
| 2026-02 | €2,858.34 | €0.00 | €3,825.16 | €1,530.07 | €749.30 | €0.00 | €49.28 | €144.05 | €0.00 | €381.22 | €1,200.00 | €2,629.58 |
| 2026-03 | €2,629.58 | €0.00 | €4,664.35 | €1,865.74 | €749.30 | €0.00 | €48.56 | €144.77 | €0.00 | €471.43 | €1,200.00 | €2,814.13 |
| 2026-04 | €2,814.13 | €0.00 | €4,683.87 | €1,873.54 | €749.30 | €0.00 | €47.84 | €145.49 | €0.00 | €471.65 | €1,200.00 | €3,010.18 |
| 2026-05 | €3,010.18 | €0.00 | €5,015.65 | €2,006.26 | €749.30 | €0.00 | €47.11 | €146.22 | -€921.90 | €561.87 | €1,200.00 | €4,236.97 |
| 2026-06 | €4,236.97 | €0.00 | €5,269.35 | €2,107.74 | €749.30 | €0.00 | €46.38 | €146.95 | €0.00 | €562.09 | €1,200.00 | €4,693.86 |
| 2026-07 | €4,693.86 | €0.00 | €5,620.65 | €2,248.26 | €749.30 | €0.00 | €45.65 | €147.68 | €1,430.10 | €562.31 | €1,200.00 | €3,931.21 |
| 2026-08 | €3,931.21 | €0.00 | €5,445.00 | €2,178.00 | €749.30 | €0.00 | €44.91 | €148.42 | €0.00 | €562.53 | €1,200.00 | €4,493.05 |
| 2026-09 | €4,493.05 | €0.00 | €5,269.35 | €2,107.74 | €749.30 | €0.00 | €44.17 | €149.16 | €0.00 | €742.75 | €1,200.00 | €4,769.28 |
| 2026-10 | €4,769.28 | €0.00 | €6,889.20 | €2,755.68 | €749.30 | €0.00 | €43.42 | €149.91 | €1,619.10 | €832.97 | €1,200.00 | €4,308.10 |
| 2026-11 | €4,308.10 | €0.00 | €7,025.80 | €2,810.32 | €749.30 | €0.00 | €42.67 | €150.66 | €0.00 | €1,013.20 | €1,200.00 | €5,367.75 |
| 2026-12 | €5,367.75 | €0.00 | €8,801.78 | €3,520.71 | €749.30 | €0.00 | €41.92 | €151.41 | €0.00 | €1,283.42 | €1,200.00 | €7,222.77 |
Supporting your plan
| Item | Explanation |
|---|---|
| Business and plan | Startende webshop. Deze voorbeeldcijfers vervangen geen marktonderzoek. |
| Revenue and seasonality assumptions | Jaar 1: €60.000 omzet exclusief btw. Controleer bezoekers, conversie, orderwaarde en verkoopkanalen. |
| Cost and investment assumptions | Vervang voorbeeldbedragen door offertes en contracten. Beginvoorraad wordt in het model op peil gehouden. |
| Funding purpose and terms | €10.000 lening voor de start, 60 maanden, 6% rente. Controleer voorwaarden en zekerheden bij je financier. |
| Risks and mitigations | Bekijk ook het voorzichtige scenario en late klantbetalingen. Beoordeel de kaspositie elke maand. |
Assumptions, sources and version
2026 · financial-plan-1.0 · v2026.1
- Indicative financial plan using your inputs; no financing approval or accountant’s assurance. The structure follows KVK and Qredits’ four budgets; Rekenbox is not affiliated with them.
- The plan starts on the first day of a month. Assets, initial inventory, start-up spending and financing occur at the start. Inventory is then maintained: purchases follow budgeted cost of sales. Depreciation is straight-line over the entered useful life and is not a tax deduction claim.
- Revenue and purchases are spread evenly across each month’s days; payment terms shift receipt or payment by the entered number of days. Fixed costs, salary and drawings are paid in the same month. Outstanding balances remain visible at the end.
- The VAT model uses invoice accounting, one sales and purchase rate, recoverable input VAT and calendar quarters or months. VAT payable falls in the next month; refunds follow your entered delay. With VAT disabled, purchase VAT increases costs and investments. KOR, cross-border VAT, private use and partial recovery need separate calculations.
- The income/corporate tax reserve is your planning percentage of positive profit. It is not a full tax assessment or loss-offset calculation. Sole-trader income tax is personal: the reserve reduces available cash, not business profit. For a BV we also show profit after the corporate-tax reserve.
- KVK — financieel plan (2026-09-06)
- KVK — exploitatiebegroting (2026-09-06)
- Qredits — financieel plan voorbeeld (2026-09-06)
- Belastingdienst — btw-aangifte en betaling (2026-09-06)
Report for your records
Turn this into a complete PDF report.
Financial plan PDF for your bank or Qredits application: all four budgets, monthly figures, funding headroom and your explanations, with sources and calculation version. €19 including VAT per dossier; included with access. The lender makes its own lending decision.
- Result with the full calculation
- Assumptions and sources, so others can verify it
- Your inputs and calculation version recorded
The same calculation as above, fully documented. View the free preview first; you only pay when you want to download the report. See pricing
For the preview, we store your inputs encrypted on our server: 30 days without an account, or until you delete it once linked to your email.
Bulk · Calculate your entire list
Save on this device for free
Understand your result
How this tool works
An investment budget lists the resources needed to start or expand a business. Equipment alone rarely represents the full amount. Initial inventory, launch costs, VAT paid before any refund and a cash buffer also need funding. This investment calculator compares those needs with owner capital, borrowing and other finance. It shows whether your stated funding covers the plan and keeps any shortfall visible instead of silently adding a loan.
Start with fixed assets. For each item, enter a description, purchase cost, residual value, useful life and VAT rate. Use supplier quotations where available and check which installation or delivery costs they include. The calculator derives straight-line business depreciation from these entries and carries it into the operating budget. The full purchase payment appears at the start of the cash forecast. This is not a calculation of tax investment allowances or special depreciation relief.
Enter opening inventory separately from one-off launch expenses. Inventory is maintained in this model: later purchases follow the budgeted cost of the goods sold. Start-up expenses reduce the first month's profit. The cash buffer is the amount you would like to keep available after initial spending. A target buffer does not create cash. Only the actual funding amounts you enter provide money for the forecast.
Next review how the investment is financed. Owner capital and a loan affect equity and monthly payments differently. For a loan, enter the annual rate, term and either annuity or linear repayment. Other funding can be equity or an interest-free loan repayable after the selected horizon. Choose its nature explicitly because this affects the forecast balance sheet and the ratios available from the completed plan.
The worked shop requires €6,000 of equipment, €3,000 of inventory and €1,000 of launch costs before VAT. Including 21% VAT paid upfront and a desired €5,000 cash buffer gives a €17,100 funding requirement. The example covers this with €7,100 owner capital and a €10,000 loan. Reduce owner capital alone by €1,000 and the forecast displays a €1,000 gap. It never treats an unfunded requirement as available money.
After balancing initial funding, inspect the later cash months. A fully funded purchase can still be followed by cash pressure when customers pay late. Test payment terms and sales scenarios, then review the minimum cash balance. Free PDF and Excel exports include investment needs and funding sources alongside operating profit and cash flow. Add quotations, loan conditions and your explanations before using the dossier in a financing discussion.
Investment budget example
Equipment of €6,000, opening inventory of €3,000 and start-up costs of €1,000 require €12,100 of payments including 21% VAT. Keeping a €5,000 buffer requires €17,100 funding. Owner capital of €7,100 plus a €10,000 loan covers it. With €6,100 owner capital the plan shows a €1,000 shortfall.
Create a funding budget
The gap remains visible and cash uses your actual inputs. Change funding or spending yourself. The calculator does not fill a shortfall with assumed income.
Common questions
How do I create an investment budget for a loan?
List supported asset, inventory, start-up and buffer needs. Match them with owner funds and loans. Enter the term and rate, then review whether forecast cash can cover the payments.
How do investment and financing differ?
Investment describes how money will be used. Financing describes where it comes from. Their totals should match the desired initial buffer.
Should the funding cover VAT?
The tool includes VAT paid upfront in initial spending. If fully recoverable, the refund appears later according to your chosen return period and delay. You still need funding until then.
Why is a cash buffer included in investment needs?
The buffer is desired headroom after initial payments. It is a funding target, not another expense or automatically created cash. Actual funding determines the money available.
What happens if funding is insufficient?
The gap remains visible and cash uses your actual inputs. Change funding or spending yourself. The calculator does not fill a shortfall with assumed income.
Which details do you need?
- Actual monthly cash movements
- Company name
- Starting month (first day)
- Horizon
- Legal form
- Monthly year-one revenue excluding VAT
- Revenue growth year 2 (%)
- Revenue growth year 3 (%)
- Annual fixed-cost growth (%)
- Scenario
- Custom revenue change (%)
- Custom fixed-cost change (%)
- Fixed assets at the start
- Initial inventory excluding VAT
- VAT on initial inventory (%)
- One-off start-up costs excluding VAT
- VAT on start-up costs (%)
- Target cash buffer after initial spending
- Owner capital
- Initial loan
- Annual loan interest (%)
- Loan term in months
- Repayment
- Other funding
- Type of other funding
- Cost of goods as % of revenue
- Staff including employer costs per month
- VAT on staff including employer costs (%)
- Premises per month
- VAT on premises (%)
- Marketing per month
- VAT on marketing (%)
- Insurance per month
- VAT on insurance (%)
- Administration per month
- VAT on administration (%)
- Other operating costs per month
- VAT on other operating costs (%)
- Monthly personal drawings (sole trader)
- Monthly gross director salary (BV)
- Director employer-cost allowance (%)
- Income/corporate tax reserve on positive profit (%)
- Customer payment term in days
- Supplier payment term in days
- Charge VAT and fully reclaim input VAT
- Sales VAT (%)
- Purchases VAT (%)
- VAT return period
- Expected VAT refund: months after period
- Cash tax reserve payments
- Business and plan
- Revenue and seasonality assumptions
- Cost and investment assumptions
- Funding purpose and terms
- Risks and mitigations
Limits of this tool
- Indicative financial plan using your inputs; no financing approval or accountant’s assurance. The structure follows KVK and Qredits’ four budgets; Rekenbox is not affiliated with them.
- The plan starts on the first day of a month. Assets, initial inventory, start-up spending and financing occur at the start. Inventory is then maintained: purchases follow budgeted cost of sales. Depreciation is straight-line over the entered useful life and is not a tax deduction claim.
- Revenue and purchases are spread evenly across each month’s days; payment terms shift receipt or payment by the entered number of days. Fixed costs, salary and drawings are paid in the same month. Outstanding balances remain visible at the end.
- The VAT model uses invoice accounting, one sales and purchase rate, recoverable input VAT and calendar quarters or months. VAT payable falls in the next month; refunds follow your entered delay. With VAT disabled, purchase VAT increases costs and investments. KOR, cross-border VAT, private use and partial recovery need separate calculations.
- The income/corporate tax reserve is your planning percentage of positive profit. It is not a full tax assessment or loss-offset calculation. Sole-trader income tax is personal: the reserve reduces available cash, not business profit. For a BV we also show profit after the corporate-tax reserve.
Year: 2026 · Version 2026.1
Sources for this tool
- KVK — financieel plan · calculation source checked 2026-09-06
- KVK — exploitatiebegroting · calculation source checked 2026-09-06
- Qredits — financieel plan voorbeeld · calculation source checked 2026-09-06
- Belastingdienst — btw-aangifte en betaling · calculation source checked 2026-09-06
Prepared by the Rekenbox product team at Winstwaker. The listed source references and calculation version make the method traceable. Report a content error Last updated: 2026-09-06. Rekenbox is a product by Winstwaker. The tool applies a calculation model to your inputs; a result or paid report is not a personal assessment by an adviser.